All Categories
Featured

Choosing HMO and PPO Insurance Coverage
1 Investopedia - How Whole Life Insurance Functions. Upgraded May 7, 2025. . Accessed June 18, 2026. 2 Thrivent Whole life insurance coverage: Pros, cons & who it's right for. Upgraded March 10, 2026. . Accessed June 18, 2026. 3 Forbes - What Is Whole Life Insurance Coverage? (& How Does it Work?) Updated December 18, 2024.
4 Forbes - What Is Variable Life Insurance? Material within this short article is provided for basic informative purposes and is not supplied as tax, legal, health, or financial advice for any individual or for any specific situation.
For complete details, including schedule and expenses of Aflac insurance coverage, please contact your regional Aflac agent/producer. Aflac life plans A68000 series/Term Life: In Arkansas, Idaho, Oklahoma, Oregon, Texas, Pennsylvania & Virginia, Policies: ICC1368200, ICC1368300, ICC1368400. In Delaware, Policies A68200, A68300 & A68400. In New York, Policies NY68200, NY68300 and NY68400.
Cheap Health Insurance Plans for Families
In Delaware, Policy A68100. In New York, Policy NYR68100. B60000/Term Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies ICC18B60200, ICC18B60300, & ICC18B60400. Not available in Delaware, Idaho, New York and Oregon. Whole Life: In Arkansas, Oklahoma, Pennsylvania, Texas & Virginia, Policies: ICC18B60C10, ICC18B60100. Not offered in Delaware, Idaho, New York and Oregon.
In Delaware, Policy Q60200M. In New York, Policy: NYQ60200M. Not offered in Virginia. Whole Life: In Arkansas, Delaware & Oregon Policy Q60100M. In Idaho, Policy Q60100MID. In Oklahoma, Policy Q60100MOK. In New York City, Policy: NYQ60100M. Not offered in Virginia. In AR, DE, ID, OK and VA: Policies ICC21-AFLLBL21 and ICC21-AFLRPL21; and Riders ICC21-AFLABR22, ICC21-AFLADB22, and ICC21-AFLCDR22.
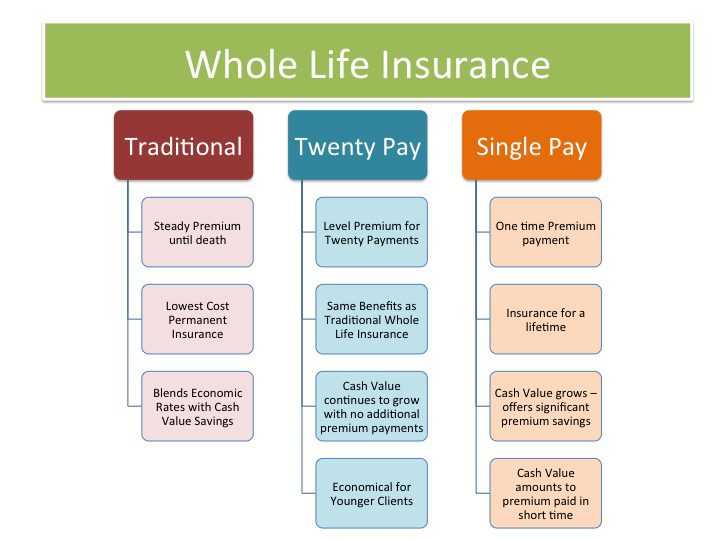
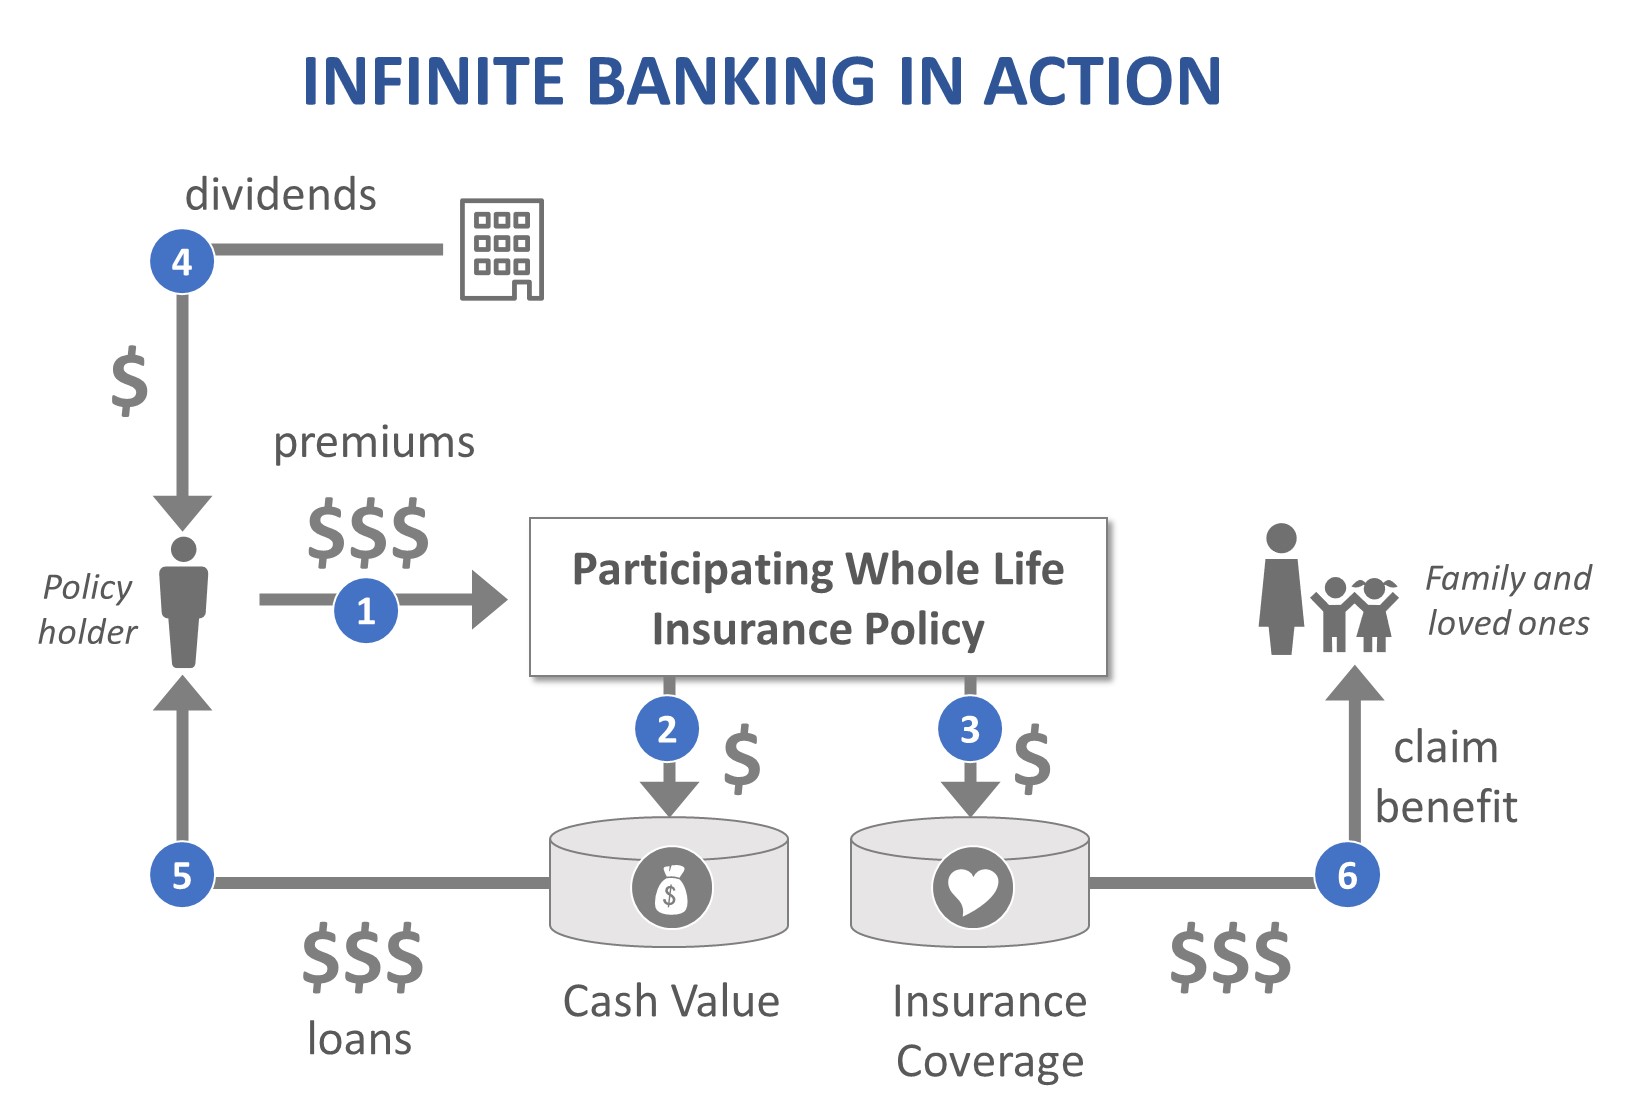
In this post, we describe what whole life insurance is and compare it to call life insurance, as well as universal life and variable life insurance coverage. Whole life insurance is one type of irreversible insurance and is really different from term life insurance coverage, which supplies protection for a specified duration only and does not develop money value. If term life insurance coverage is the most typical kind of life insurance coverage, entire life insurance is the oldest kind of irreversible life insurance coverage.
The bigger your money value, the larger the loan you can take. You can utilize your money worth to supplement your other retirement income. Entire life insurance coverage is the only form of life insurance coverage that guarantees of the following: The survivor benefit won't go down The policy will not expire as long as premiums are paid Your premiums won't
increase Your costs will never increase The insurer ensures that the money value of your entire life insurance coverage policy will grow in time. figure out just how much your cash worth ought to grow based on current rate of interest, which, naturally, vary with time. allow you to invest funds in policy subaccounts, comparable to shared funds. Your cash value will increase orreduce, depending on the efficiency of these subaccounts. What takes place if performance of the cash worth of your universal or variable life policy drops? Who needs to ante up more superior to keep your policy in force? You do. Neither option is excellent. If you have a whole life policy, you will not have to make those dreadful choices. The premium, money worth, and survivor benefit are all guaranteed. And did you know you can discover precisely what your guaranteed premium, money value and death benefit will be at any point in time before you decide if it makes good sense to begin a whole life policy? Just request a FREE, no-obligation Analysis here to take the initial step. In such a way, it resembles getting an earnings tax refund. Now, dividends are not guaranteed. It's imaginable an insurance coverage company might have a dreadful, dreadful, no excellent, very bad year . In reality, that's what the company prepares for. And every year that'sbetter than they planned, they can pay a dividend. Get Your FREE Report! Get immediate access to the FREE 18-page Unique Report that reveals how super-charged dividend paying whole life insurance coverage lets you bypass Wall Street, fire your lender, and take control of your monetary future. You get to tell the insurance coverage business what to do with your dividend. and this just may be the neatest thing given that cupcakesyou can have them utilize your dividend to purchase more insurance for you insurance coverage you'll never have to pay another premium for again. Think of that! You can purchase extra insurance that's paid up, suggesting no more premiums will be due on that additionever. If that reminds you of the 8th wonder of the worldcompound interestthat's due to the fact that the principle is exactly the same. Only paid up whole life insurance additions build both your policy's money worth and your survivor benefit. You can find out more here about dividend-paying entire life insurance coverage, which lots of people discover particularly exciting. Term life insurance premiums go upsometimes drasticallywith every brand-new term, because much of the cost of insurance coverage is based upon how most likely you are to die at a given age, and as you age, that likelihood increases. Universal and variable insurance coverage premiums can go up, tooagain, in some cases drasticallyif money worth drops dueto low rate of interest or poor investment performance. So you may be asking, "If it costs more to guarantee my life with every passing year, how can a life insurance coverage business promise my premiums will never go up?" The response is elegantly simpleand it assists explain why whole life insurance is more costly than term insurance coverage in the early years of the policy.

Latest Posts

Building Financial Security with Whole Life Insurance
PPO vs HMO Health Insurance Plans
Choosing HMO and PPO Insurance Coverage