All Categories
Featured


IUL Policy Options for Future Security
How much coverage does my family really require, based on earnings, financial obligations, and dependents? Am I still within my VGLI eligibility window specifically, the 240-day no-health-review period? Do I have a service-connected special needs that could make me qualified for VALife? Would I receive more favorable rates through a private insurance provider, or would health.
concerns work versus me? Do I want term protection, long-term coverage, or a mix? What coverage do I already have through VGLI, VALife, a company, or existing savings that should factor into the total? Am I comparing programs based upon my actual eligibility, not just general assumptions about age or health? No. VGLI is the separate group term program available to qualified veterans after they leave service it's created to get where SGLI leaves off, but you need to look for it separately, within a specific window. For a better look at SGLI itself, consisting of how it compares to private coverage while you're still serving, see SGLI vs. Yes. VGLI premiums are based upon your age and the amount of coverage you choose, and rates typically increase at older ages. has present rate info. Yes. VA explicitly permits requesting both. Lots of veterans use this to get more overall protection than VGLI alone supplies, or to compare their choices. VGLI, by comparison, is term insurance coverage, not entire life. There's no universal number it depends upon your earnings, debts, dependents, existing protection, and goals. LifeCoverPath's calculator can help you resolve those aspects and get an individualized, instructional price quote. No. LifeCoverPath is an independent.
instructional resource operated by VetLife LLC as part of its Veteran Life Insurance service. Department of Veterans Affairs, the U.S. military, or any federal government agency. For current rates, eligibility guidelines, and applications, constantly go straight to VA's own resources:. You complete life insurance coverage starts 2 years after you apply.
Cheap Individual Health Insurance Quotes in the US
Entire life insurance coverage offers protection for life and might construct cash worth. Browsing life insurance can be tough, specifically for veterans returning to civilian life. Veterans often face different money situations that need mindful thought about life insurance.
This assists provide assurance during difficult times. Life insurance coverage provides veterans and their households important security and assurance. It primarily does this by offering a monetary safety internet. This occurs through a tax-free survivor benefit that goes to chosen recipients when the policyholder passes away. This cash helps loved ones deal with the costs that come with
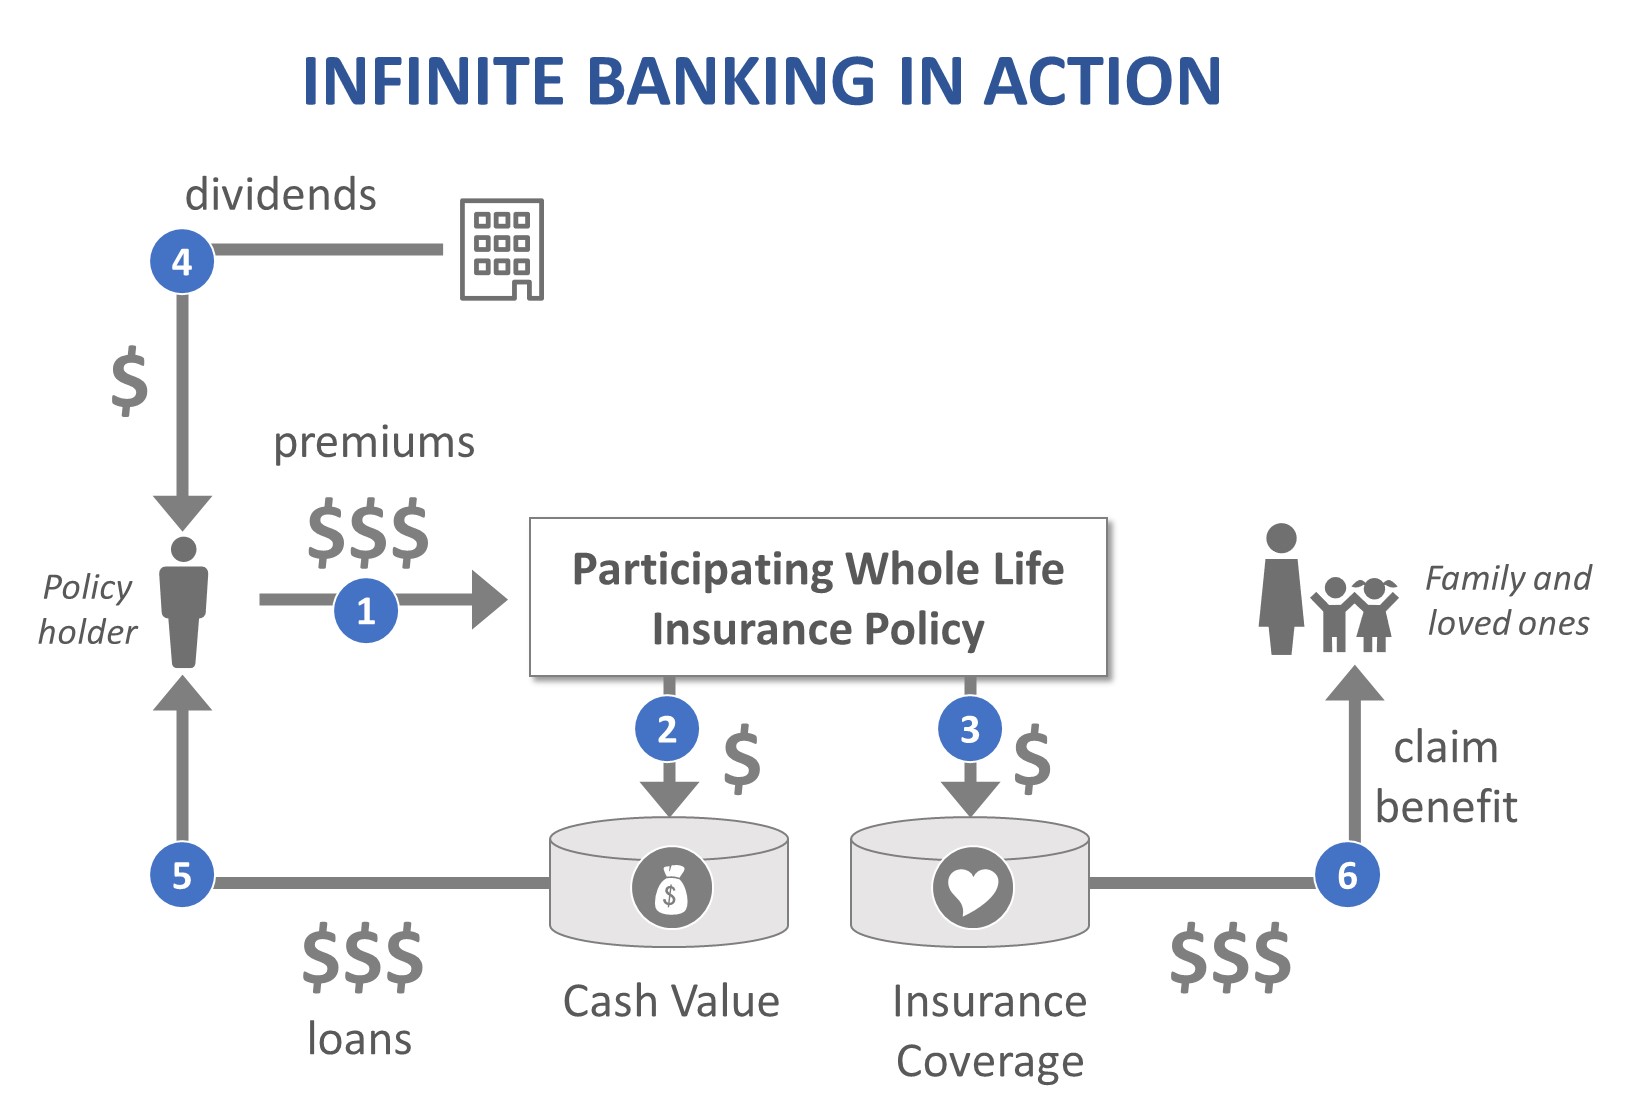
losing their primary income earner. The death benefit, some life insurance policies, like whole life insurance coverage, construct money worth over time. This money value grows without being taxed until you take it out. This feature can be a fantastic financial tool. You can utilize it for additional income in retirement, paying for your child's education, or dealing with unexpected expenses. They must believe about things like debts, just how much cash their dependents will require, and their overall financial goals. Dealing with a financial advisor who understands veterans can really assist in this procedure. This cautious check helps ensure that veterans get enough coverage to secure their households without dealing with high costs. Deciding just how much protection you require truly depends on your personal situation and financial obligations. An excellent standard is to search for protection that is multiple times your yearly income. This helps ensure your relative can keep their lifestyle after you're gone. However remember, this is simply a starting point. Also, consider expenses for raising a household, like child care and education. Your individual life insurance should match these monetary tasks so your recipients have enough assistance. The main goal is to replace your income and develop a safeguard for the future, so you and your loved ones can feel safe and secure and not stressed. These consist of disability payments, healthcare services, and assist with education. These benefits are crucial for veterans'health and joy. Nevertheless, it is likewise essential to believe about how they affect life insurance coverage requires. Veterans getting VA impairment benefits or military pensions may not require as much money if they pass away. Each policy has special features and advantages. The 2 main types are term life insurance and long-term life insurance coverage. It is essential to understand the differences in between these types so you can select the very best one for your financial objectives, family requirements, and budget.
Veterans need to consider what matters most to them and just how much threat they are willing to take. Term life insurance is a popular choice due to the fact that it is inexpensive and easy to understand. It gives monetary defense for a set time, normally 10, 20, or thirty years. This duration is called the "term." If the individual who owns the policy dies throughout this term, the beneficiaries will get a survivor benefit stated in the policy. This makes it an excellent choice for veterans who wish to save money. Protection is only for the term of the policy. If the insured individual lives longer than the term, the policy ends, and no death advantage is given. Term life insurance permits policyholders to alter protection as they require. While term life insurance coverage is terrific for momentary needs, it is essential to think of if you might need protection for your whole life, particularly as a more youthful veteran. Whole life insurance coverage is a kind of irreversible life insurance. It gives protection for the whole life of the person insured. This indicates it uses long-lasting financial security. Term life insurance coverage ends after a certain time. Entire life insurance remainsactive as long as the premiums are paid. This method, recipients will constantly receive a death benefit, no matter when the insured individual dies. An unique advantage of whole life insurance is the money value that grows over time. This account grows without being taxed immediately. Individuals do not need to pay taxes on this development until they take cash out. Some whole life insurance coverage policies can likewise provide dividends. Dividends are a share of the profits of the insurance coverage business, and they are returned to policyholders.

Life insurance coverage provides veterans and their households essential security and peace of mind. The death advantage, some life insurance policies, like entire life insurance, build cash worth over time. The 2 primary types are term life insurance and irreversible life insurance.
Term life insurance coverage permits policyholders to change protection as they need. While term life insurance coverage is terrific for momentary requirements, it's crucial to think about if you may need security for your entire life, particularly as a more youthful veteran. Whole life insurance coverage is a kind of long-term life insurance coverage.

Latest Posts

Building Financial Security with Whole Life Insurance
PPO vs HMO Health Insurance Plans
Choosing HMO and PPO Insurance Coverage